Deemed Dividend Distribution in Cyprus: 2026 Rules
By Kyriacos Socratous, BA ACA, Managing Director, Evidentrust Financial Services Ltd · Updated October 2026
Cyprus abolished deemed dividend distribution (DDD) for company profits earned from 1 January 2026, but it has not disappeared yet. Under the transitional rules, 70% of a company's 2024 profits is deemed distributed on 31 December 2026, and 70% of its 2025 profits on 31 December 2027. Special Defence Contribution (SDC) at 17% applies to the deemed amount, but only to the extent the profits are attributable, directly or indirectly, to shareholders who are both Cyprus tax resident and Cyprus domiciled. Profits earned from 2026 onwards carry no deemed distribution, and actual dividends paid out of those profits are subject to SDC at 5%.
This page explains which profits are still caught, who is affected, how the 2024 deemed distribution works, and what to decide before 31 December 2026.
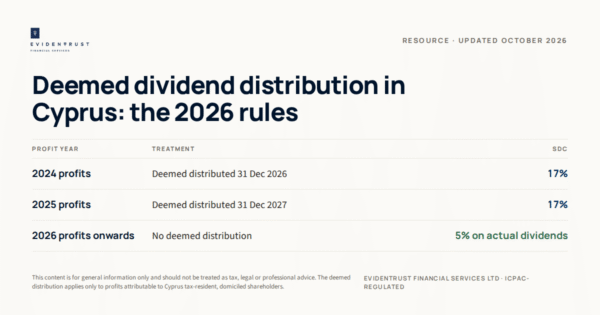
| Profit year | Treatment | SDC rate |
|---|---|---|
| 2024 profits | 70% deemed distributed on 31 December 2026 | 17% |
| 2025 profits | 70% deemed distributed on 31 December 2027 | 17% |
| 2026 profits onwards | No deemed distribution | 5% on actual dividends |
Is deemed dividend distribution still in force in Cyprus?
For new profits, no. The 2026 tax reform removed the deemed distribution rule for profits earned from the 2026 tax year onwards. A Cyprus company that makes a profit in 2026 will not be treated as having distributed part of it simply because time has passed.
For profits already earned, yes. Profits for 2024 and 2025 remain within transitional rules, so the familiar mechanism still runs for two more cycles: once on 31 December 2026 for 2024 profits, and once on 31 December 2027 for 2025 profits.
That is why this is a live issue for company owners this year, even though the regime itself has been abolished.
Which profits, which rate: the transitional rules
The rate depends on the year in which the profit was earned, not the year in which it is paid out.
- 2024 profits: 70% is deemed distributed on 31 December 2026, with SDC at 17% on the deemed amount.
- 2025 profits: 70% is deemed distributed on 31 December 2027, with SDC at 17%.
- 2026 profits onwards: no deemed distribution. When the company actually pays a dividend from these profits, SDC applies at 5% for shareholders who are subject to SDC.
The practical consequence is that a company's retained earnings now sit in layers, each with its own SDC treatment. Keeping track of which year a dividend is paid from matters more after the reform than before it.
Who the deemed distribution applies to
Cyprus tax-resident and Cyprus-domiciled shareholders
The deemed distribution only bites on the proportion of profits attributable, directly or indirectly, to individual shareholders who are both Cyprus tax resident and Cyprus domiciled. If all of a company's ultimate shareholders fall into that category, the full 70% calculation applies.
Non-dom and non-resident shareholders
Shareholders who are not Cyprus tax resident, or who are Cyprus tax resident but not Cyprus domiciled (non-doms), are outside SDC on dividends. The share of profits attributable to them is not subject to the deemed distribution. A company owned entirely by non-doms or non-residents is therefore not affected, although the position should still be checked and documented rather than assumed.
Holding structures
Because the test looks at shareholders directly or indirectly, it reaches through Cyprus holding companies to the individuals at the top of the structure. A Cyprus operating company owned by a Cyprus holding company, which is in turn owned by a Cyprus-domiciled individual, is still within scope. Mixed ownership means a proportionate calculation.
How the deemed distribution of 2024 profits works
The 70% base
The starting point is 70% of the company's accounting profit for 2024 after tax, as adjusted under the SDC rules. The deemed distribution date is two years after the end of the tax year, which for 2024 profits is 31 December 2026.
Actual dividends paid before 31 December 2026
Actual dividends paid out of 2024 profits before the deemed distribution date reduce the amount that is deemed distributed. In practice, this is the main decision for owners this year: pay an actual dividend from 2024 profits, or let the deemed distribution apply. Both routes lead to SDC at 17% on the relevant amount; the difference is whether the cash actually leaves the company.
The company pays the SDC on the deemed distribution on behalf of the relevant shareholders.
A simplified example
A Cyprus company made an after-tax accounting profit of €100,000 in 2024 and has paid no dividend from it. Its only shareholder is a Cyprus tax-resident, Cyprus-domiciled individual.
- Deemed distribution on 31 December 2026: 70% × €100,000 = €70,000
- SDC at 17%: €11,900, paid by the company on the shareholder's behalf
- If the same company were owned 50% by a non-dom, the deemed distribution would apply only to the 50% attributable to the domiciled shareholder: €35,000, with SDC of €5,950.
This example is simplified and ignores the statutory adjustments to the profit base. Real figures depend on the company's accounts and shareholder position.
Dividends paid later out of pre-2026 profits
Profits earned up to 31 December 2025 keep their 17% SDC treatment for longer than the deemed distribution itself. Dividends paid out of those profits remain subject to SDC at 17% where they are received on or before 31 December 2031, for shareholders who are subject to SDC.
Dividends from profits earned from 2026 onwards are subject to SDC at 5%. A company with retained earnings from both periods should therefore record, for every dividend it pays, which year's profits it comes from.
What to do before 31 December 2026
- Confirm the 2024 profit figure. The calculation starts from the 2024 audited accounts. If the 2024 audit is not yet signed, that is the first item.
- Map the shareholders. Identify, through any holding companies, which ultimate shareholders are Cyprus tax resident and Cyprus domiciled, and which are not.
- Check what has already been paid. List any dividends already paid out of 2024 profits.
- Decide on an actual dividend. Compare paying a dividend from 2024 profits before year-end with letting the deemed distribution apply, including the cash position of the company.
- Record the decision. Board minutes and dividend records should state which year's profits each dividend is paid from.
- Plan the 2025 cycle now. The same decision comes round for 2025 profits by 31 December 2027.
Using our DDD calculator
Our deemed dividend distribution calculator applies only to 2024 and 2025 profits under the transitional rules. Profits from 2026 onwards are not subject to deemed distribution, so the calculator should not be used for them.
Frequently asked questions
Has Cyprus abolished deemed dividend distribution?
Yes, for profits earned from 1 January 2026. Profits earned in 2024 and 2025 remain within transitional rules, so deemed distributions will still arise on 31 December 2026 and 31 December 2027.
When are 2024 profits deemed distributed?
On 31 December 2026, for 70% of the relevant profit. Actual dividends paid out of 2024 profits before that date reduce the deemed amount.
When are 2025 profits deemed distributed?
On 31 December 2027, for 70% of the relevant profit, on the same basis as 2024 profits.
What SDC rate applies to the deemed distribution of 2024 and 2025 profits?
17% on the gross deemed dividend, to the extent the profits are attributable to Cyprus tax-resident and Cyprus-domiciled shareholders.
What is the SDC rate on dividends from profits earned from 2026?
5%, for shareholders who are subject to SDC. There is no deemed distribution for these profits.
Does deemed distribution apply to non-dom shareholders?
No. It applies only to the proportion of profits attributable to shareholders who are both Cyprus tax resident and Cyprus domiciled. Non-doms and non-residents are outside SDC on dividends.
What rate applies if a company pays a dividend in 2027 out of 2024 profits?
Dividends paid out of profits earned up to 31 December 2025 remain subject to SDC at 17% where received on or before 31 December 2031, for shareholders subject to SDC.
Speak to Evidentrust before 31 December
If your company has retained profits from 2024 or 2025 and Cyprus-domiciled shareholders, the decision on dividends needs to be made before year-end. We can review the 2024 position, the shareholder structure and the options in one meeting.
Book a consultation with Evidentrust
Related reading: Cyprus non-dom vs holding company
Sources: Cyprus Tax Department ·
This article is for general information only and does not constitute tax, legal or professional advice. Individual circumstances vary; please contact Evidentrust or a qualified adviser before taking action.
About the author. Kyriacos Socratous, BA ACA, is Managing Director of Evidentrust Financial Services Ltd, an ICPAC-regulated accounting, audit and tax firm in Limassol. He advises Cyprus companies, holding structures and international clients on audit, tax and compliance.
Important: deemed dividend distribution was abolished for profits earned from 2026. This calculator applies only to 2024 and 2025 profits under the transitional rules (deemed distribution dates 31 December 2026 and 31 December 2027). Read the 2026 rules.


Visit the MyCyprusTax for more information on how to submit you income tax form.
Visit the Cyprus Tax Department for more information on how to calculate your taxes.